
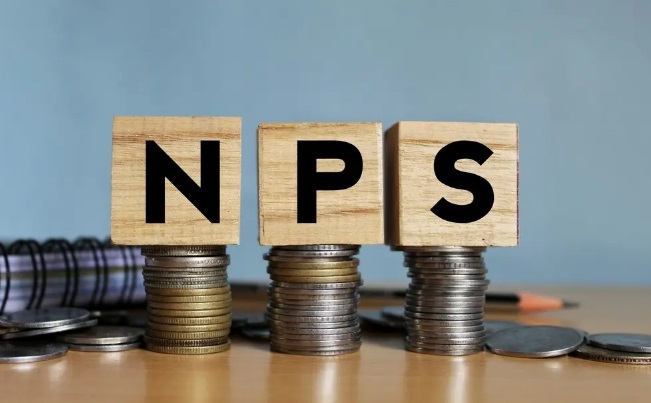
New Delhi: Investing for a secure and comfortable retirement is a priority for most people, but with so many choices, it can be difficult to determine which one is ideal for your requirements. Two of the most trending investment channels today are the National Pension System (NPS) and Systematic Investment Plans (SIP). Although both are meant for wealth creation, they do so differently, each with its own strengths. In this article, we will compare NPS and SIP and guide you on which one is the best investment scheme for your retirement plans.
Although both NPS and SIP are good investment schemes, they are suited for different financial requirements and objectives. The National Pension System (NPS) is particularly geared towards ensuring a secure retirement income, providing long-term benefits to those who wish to ensure financial security after retirement. SIP, however, is more flexible and can be utilized for a variety of financial goals, including creating wealth, funding education, or buying a house. Therefore, knowing your individual financial needs, risk appetite, and time horizon will assist you in deciding on the superior plan among NPS and SIP.
What is NPS
The National Pension System (NPS) is a government-sponsored pension system that aims to deliver retirement benefits to those in the private, public, and unorganised sectors. The scheme persuades people to save on a regular basis during their working lives, with the corpus at their disposal at the time of retirement.
The funds contributed to NPS are invested in a combination of government securities, equities, and corporate debt. The greatest advantage of NPS is that it provides both tax relief and a structured pension at the time of retirement. You can have a choice of a Tier I (locked-in) and Tier II (flexible) account. NPS is suitable for those who would like a well-disciplined, long-term investment plan focusing on retirement funds.
What is SIP
A Systematic Investment Plan (SIP), however, is a way of investing a constant amount periodically in mutual funds. Investors can invest in debt or equity mutual funds by paying small amounts every month through SIPs. SIPs are extremely popular among millennials because they are so easy and simple to use. The money invested is credited automatically from your bank account and utilized to purchase units of a mutual fund scheme of your choice. The major benefits of SIP are the compounding power, rupee cost averaging, and flexibility in investing any amount.
Major Differences Between NPS and SIP
1. Investment Objective:
- NPS is mainly retirement planning-oriented. The money is invested with the aim of building wealth over the long term, which is later transferred into a pension post-retirement.
- SIP is more flexible and may be utilized for multiple objectives such as retirement, house purchase, or studies. SIP is used for wealth accumulation in a medium to long-term period but is not limited to retirement savings.
2. Tax Benefits:
- NPS offers great tax advantages. Contributions of up to Rs 1.5 lakh are eligible for tax deduction under Section 80C of the Income Tax Act. Moreover, you can also take an additional tax benefit of up to Rs 50,000 under Section 80CCD(1B) for NPS (Tier I account) contributions.
- SIP investments in Equity-Linked Savings Schemes (ELSS) are also eligible for tax deductions under Section 80C, with the same Rs 1.5 lakh limit. But there is no extra benefit as in NPS.
3. Return Potential
- NPS has a balanced portfolio where there is maximum 50% exposure to equities. This equity exposure guarantees higher growth potential but within limits to prevent market risks.
- SIP provides you with an opportunity to invest in mutual funds with 100% equity exposure or a combination of equity and debt. While this provides more returns, it also involves greater risks. Depending on the kind of mutual fund selected and market conditions, the return from SIP over a period of time will vary.
4. Liquidity and Flexibility
- NPS has a lock-in period. The corpus is available only after the subscriber reaches 60 years or at the time of retirement, which makes it less flexible as an investment.
- SIP, on the other hand, provides flexibility. You can withdraw your investments whenever you want without any penalty, though it can affect your long-term returns if not done cautiously.
Risk Factors
NPS qualifies as a low-to-moderate-risk investment since it is diversified across government securities, bonds, and equities. It exposes the investment to equity up to 50%, which protects the investment from excessive market volatility.
– SIP involves more risk, particularly if you invest in equity-based mutual funds. SIP returns depend directly on the performance of the market, and thus you could have times when the returns are very volatile.
6. Minimum Investment
- NPS has a minimum contribution of Rs 500 in Tier I accounts. It can be slightly higher for certain investors, but it is designed for long-term savings.
- SIP can be as low as Rs 500 a month, and you can invest at your convenience, so it is more suitable for small investors.
It comes down to your investment objectives, risk appetite, and retirement strategy whether to go for NPS or SIP. If you are more concerned about creating a stable pension corpus for your retirement and prefer the discipline of a long-term, structured investment, NPS is the best bet. The tax advantages and assured returns make it the best for those seeking a safe, government-guaranteed scheme.
But if you desire flexibility, greater return potential, and want to diversify your portfolio, SIP in mutual funds can be the preferred option. SIPs provide greater control over your investments and are ideal if you want to build wealth for different financial objectives, including retirement.
Finally, NPS and SIP are both good investment strategies, but are used for different purposes. If you are looking for retirement savings with security and tax advantages, NPS is the choice. If you opt for flexibility with greater potential for returns with medium risk, SIP in mutual funds would be the best option. Either one or both can be combined for a balanced wealth creation and retirement planning.